Commercial property owners · First edition 2026
A property can look successful while cash is being lost inside the operation.
This book separates the four economic engines of a commercial property, measures each one with thirty defined figures, screens fifty ways to improve cash flow and value, and evaluates cost segregation inside the taxpayer's full holding period — with a framework that is allowed to say no.
- ›For owners and managing partners of income-producing property
- ›Solves the problem of four reports that never get read together
- ›Teaches the Capital Recovery Scan, 30 measures, 50 strategies
- ›Written by someone who asks what is underneath the numbers
- 4
- economic engines
- 30
- defined measures
- 50
- strategies
- 8
- appendices
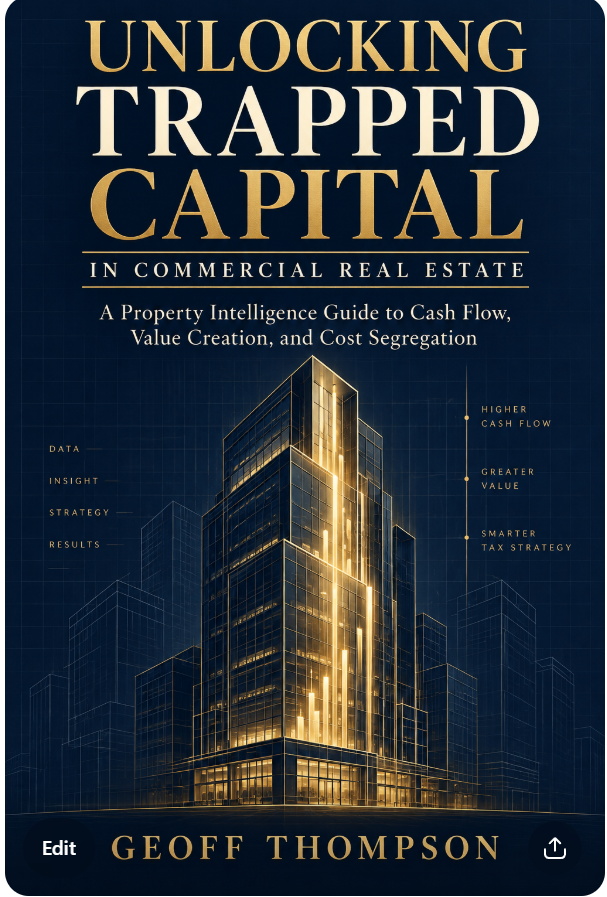
20 chapters · 8 appendices · First edition 2026
Where capital becomes trapped
Six places capital quietly becomes trapped.
Commercial property can produce rent, build equity, create tax deductions, and preserve long-term wealth. It can also conceal weak collections, inefficient expenses, financing pressure, missed depreciation, poor records, and badly timed decisions.
Revenue leakage
Loss to lease, concessions never withdrawn, uncollected reimbursements, unbilled ancillary income, slow lead response.
Expense leakage
Unbenchmarked utilities, auto-renewing vendor contracts, deferred maintenance that turns into capital spend, unappealed assessments.
Capital expenditure leakage
Projects funded without a yield-on-cost hurdle, tenant improvement packages priced without the full effective-rent math.
Financing leakage
A maturity nobody diaried, coverage drifting toward covenant, reserves sized by habit instead of by risk.
Tax and depreciation leakage
Assets sitting in 39-year life that belong in shorter classes, missed partial dispositions, no lookback review.
Exit leakage
Recapture discovered at closing, a data room assembled in a panic, a sale timed against the taxpayer instead of for them.
Operations
What is the property producing now?
Evidence · Rent roll, general ledger, bank activity, trailing twelve months
Common mistake · Treating projected rent as collected income
Financing
What must the property pay, and when?
Evidence · Loan documents, amortization schedule, covenants, maturity calendar
Common mistake · Looking at interest rate without maturity and coverage
Tax
What does the owner keep after tax?
Evidence · Tax basis, depreciation schedules, returns, improvement records
Common mistake · Treating a deduction as guaranteed cash
Exit
What happens when ownership or debt changes?
Evidence · Value estimate, debt payoff, hold period, sale assumptions
Common mistake · Ignoring transaction costs, recapture, or timing
The four engines affect one another, but they do not measure the same thing. A large deduction does not repair weak collections. Rising value does not guarantee spendable cash. Strong NOI does not eliminate a balloon payment.
The five questions that govern the book
Simple enough to remember. Rigorous enough to organise a full property review.
What is the property producing now?
Collected rent, other income, vacancy, concessions, credit loss, operating expenses, NOI, debt service, reserves, owner cash flow — on a trailing twelve-month basis where possible. A pro forma describes an expectation. A budget describes a plan. A trailing statement describes what happened. You may need all three. You should never confuse them.
Where is cash flow or value leaking?
Leakage is any preventable loss, delay, misclassification, or failure to capture value — operational, contractual, financial, tax-related, or informational. Not every disappointing result is leakage. The test is whether better information or action could reasonably improve the result.
Which measure confirms the problem?
Concern is a starting point, not a conclusion. If expenses feel out of control, calculate the operating expense ratio by category over time. If refinancing is the worry, review coverage, debt yield, loan-to-value, balance, and maturity. You do not need all thirty measures. You need the right one, calculated consistently from reliable evidence.
Which strategy addresses it?
An operating problem needs an operating response. A loan problem needs a financing response. A tax-timing opportunity needs qualified tax analysis. Cost segregation is a major capital-recovery tool, but it is not a universal repair kit.
What evidence is needed before the owner acts?
Leases, rent roll, bank statements, general ledgers, invoices, closing documents, appraisals, loan agreements, depreciation schedules, prior returns, plans, and placed-in-service support. This is where most opportunities are lost. Good records do not merely support compliance — they increase the number of options available later.
Part One builds the baseline. Nothing is recommended before it exists.
The anchor property
One 12,000 sq ft medical office, carried through every chapter.
Eight suites, acquired for $3,000,000, financed with a $2,100,000 loan at an illustrative 6.75 percent over 25 years. Every figure in the book traces back to it, so the arithmetic stays consistent and you can watch which engine moves when one assumption changes.
| Gross potential rental income | $420,000 |
| Vacancy and credit loss (5%) | −$21,000 |
| Other property income | $12,000 |
| Effective gross income | $411,000 |
| Operating expenses | −$150,000 |
| Net operating income | $261,000 |
| Annual debt service | −$174,110 |
| Capital reserve | −$12,000 |
| Before-tax cash flow | $74,890 |
It is not a benchmark, and it is not advice
The recurring example keeps the arithmetic consistent. It is not a benchmark, appraisal, loan quote, engineering conclusion, or tax-return position. Replace every input with verified property and taxpayer facts before acting.
If your trailing statement shows $261,000 of NOI and your lender's shows $245,000, the correct response is not to choose the higher number. It is to understand the convention and the evidence behind each one.
Part two · the thirty measures
Every measure, its equation, and its figure on the anchor property.
All thirty, as the book defines them. In the book each one also carries its decision use and the specific action it puts in front of the owner.
Income and operating performance
Chapter 4Gross Potential Income
Caution · Separate rental income from other income.
Market rent per space × rentable spaces
$420,000
$35 per rentable sq ft across 12,000 sq ft
Vacancy and Credit Loss
Caution · Use economic loss, not only physical vacancy.
Gross potential income × vacancy and credit-loss rate
$21,000
5% of gross potential income
Effective Gross Income
Caution · Keep reimbursements and ancillary income consistently classified.
Gross potential income − vacancy and credit loss + other income
$411,000
$420,000 − $21,000 + $12,000
Operating Expense Ratio
Caution · Exclude debt service, income tax, and depreciation.
Operating expenses ÷ effective gross income
36.5%
$150,000 ÷ $411,000
Net Operating Income
Caution · NOI is before debt service, depreciation, and income tax.
Effective gross income − operating expenses
$261,000
$411,000 − $150,000
NOI Margin
Caution · Compare only properties using consistent expense classifications.
Net operating income ÷ effective gross income
63.5%
$261,000 ÷ $411,000
Break-Even Ratio
Caution · A lender may use a different definition. Label the convention.
(Operating expenses + annual debt service) ÷ EGI
78.9%
($150,000 + $174,110) ÷ $411,000
Value and market pricing
Chapter 5Capitalization Rate
Caution · Use stabilized or actual NOI consistently with the value date.
Net operating income ÷ current market value
8.03%
$261,000 ÷ $3,250,000 indicated value
Gross Rent Multiplier
Caution · Does not account for operating expenses. A screen only.
Purchase price ÷ annual gross scheduled rent
7.14
$3,000,000 ÷ $420,000
Price per Rentable Square Foot
Caution · Do not mix gross building area and rentable area.
Purchase price ÷ rentable square feet
$250
$3,000,000 ÷ 12,000 sq ft
Yield on Cost
Caution · Project cost includes acquisition and capitalized improvements.
Stabilized NOI ÷ total project cost
8.13%
$261,000 ÷ $3,210,000
Value Created from NOI Improvement
Caution · Only durable NOI changes support value. The cap rate is an assumption.
Change in NOI ÷ market capitalization rate
$312,500
A durable $25,000 NOI increase at an 8% cap rate
Debt and refinance capacity
Chapter 6Loan to Value
Caution · Value is an opinion. State its date and its basis.
Loan balance ÷ current market value
64.6%
$2,100,000 ÷ $3,250,000
Loan to Cost
Caution · Cost and value are different denominators. Do not interchange them.
Loan amount ÷ total project cost
65.4%
$2,100,000 ÷ $3,210,000
Debt Service Coverage Ratio
Caution · The covenant test. Confirm the lender's NOI convention.
Net operating income ÷ annual debt service
1.50×
$261,000 ÷ $174,110
Debt Yield
Caution · Independent of rate and amortization. Repricing alone does not move it.
Net operating income ÷ loan balance
12.43%
$261,000 ÷ $2,100,000
Annual Debt Service
Caution · Model the loan, not the payment.
Monthly principal and interest payment × 12
$174,110
$2,100,000 at an illustrative 6.75% over 25 years
Remaining Loan Balance
Caution · Balance at maturity is the number that governs a refinance.
Original principal compounded less amortizing payments
≈$1,908,184
After the stated amortization period
Investor returns
Chapter 7Before-Tax Cash Flow
Caution · Reserves are not optional in this line.
NOI − annual debt service − recurring capital reserves
$74,890
$261,000 − $174,110 − $12,000
Cash-on-Cash Return
Caution · A one-year measure. It does not capture sale proceeds.
Before-tax cash flow ÷ initial cash equity
6.75%
$74,890 ÷ $1,110,000
Equity Multiple
Caution · Does not account for timing.
Total equity distributions ÷ total equity invested
1.75×
≈$1,940,126 ÷ $1,110,000 over five years
Internal Rate of Return
Caution · Do not manufacture IRR through an unrealistic exit value.
IRR of dated or periodic equity cash flows
≈13.2%
Five-year before-tax illustration with stated sale assumptions
Net Present Value
Caution · State the discount rate, periods, and terminal value assumptions.
Sum of discounted future cash flows − initial investment
≈$257,436
At an 8% required return, same five-year illustration
Tax and after-tax measures
Chapter 8Depreciable Basis
Caution · Land is never depreciable. The allocation must be supportable.
Purchase basis − land + capitalized acquisition costs + improvements
$2,400,000
With a separate $600,000 land allocation
Adjusted Tax Basis
Caution · Track it by asset class, not as one building number.
Initial tax basis + capital improvements − accumulated depreciation
Schedule-driven
The figure that governs gain at sale
Taxable Property Income
Caution · Three different income definitions. Never substitute one for another.
Taxable revenue − deductible expenses − depreciation − interest
Schedule-driven
Not the same figure as NOI or as cash flow
Straight-Line Depreciation
Caution · The baseline you must build before any study is evaluated.
Depreciable building basis ÷ applicable recovery period
≈$70,769
Per full year in the simplified illustration
Reclassified and Accelerated Depreciation
Caution · Deduction generated and deduction usable are two different numbers.
Depreciation with study − depreciation without study
≈$672,308
Additional first-year deduction in the illustration
After-Tax Cash Flow
Caution · The only cash figure that reflects what the owner keeps.
Before-tax cash flow − income tax effects
≈$56,575
Without a study, in the illustrated year
After-Tax Internal Rate of Return
Caution · The measure a cost segregation decision should ultimately turn on.
IRR of after-tax cash flows including sale effects
Model output
The full-hold test, recapture included
Each measure also carries its decision use and the owner action that follows.
The Capital Recovery Scan
The diagnostic that unifies the book, in seven steps.
It begins with the owner's pressure and routes the property into the right analysis. It is built to produce three conclusions: act, investigate further, or do not pursue.
Define the decision and deadline
State it in one sentence, with a date, an amount where possible, and the consequence of no action. “Determine whether the property can refinance by March 31 without an additional partner contribution” beats “we need more liquidity.”
Establish the baseline
Actual operating, debt, tax, and capital records. For the anchor property: $411,000 EGI, $150,000 operating expenses, $261,000 NOI, roughly $174,110 annual debt service, $12,000 reserves, about $74,890 before-tax cash flow.
Classify the pressure
Operating, financing, tax, capital-project, or exit. Issues can sit in more than one lane, but the lanes are never blended. A tax strategy may improve retained cash; it does not reverse an insurance increase inside NOI.
Quantify the opportunity
Dollars, timing, cost, and confidence. A lease audit might identify $18,000 of missed annual billings. A vendor rebid might be a high-confidence $9,000. A refinance might cut debt service $15,000 a year and cost $80,000 to close.
Identify evidence and owners
Name the document that proves each item and the person accountable for producing it. An opportunity without an evidence source is a hypothesis.
Compare action, alternative, and no action
Three columns, same assumptions, same measurement date. No action is a real option and has to be modelled like one.
Verify the result
Executed leases, billing records, deposits, aging, trailing operating statements. Compare actual collections and recurring cost against the approved case.
The three clocks
The monthly clock
Billed rent against collected rent, concessions, delinquency, vacancy, expense categories, work orders, capital spending, reserves, debt payments. One month rarely proves a trend, but it reveals the question worth investigating. If collections fall while physical occupancy holds steady, economic vacancy is rising even though the building looks full.
The trailing twelve-month clock
The most recent full year of actual performance, stripped of seasonality and isolated events. If your TTM shows $261,000 of NOI and the lender's statement shows $245,000, the answer is not to pick the higher number. It is to understand the convention and evidence behind each one.
The life-cycle clock
Acquisition, placement in service, renovation, tenant buildout, rollover, refinance, casualty, ownership change, sale. Each affects several engines at once. This clock is what prevents you from asking a specialist to reconstruct years of history under a deadline.
The ten problem routes
Intake classifies the owner's concern into one or more recurring routes. The classification determines the first set of questions, not the final answer.
Liquidity or weak cash flow
Broad Capital Recovery Scan
Refinance, DSCR, or maturity pressure
Refinance Liquidity Analysis
Renovation or major capital spending
CapEx Tax Recovery Review
Large tenant-improvement commitments
TI Recovery Review
Is cost segregation worthwhile?
CSS Go or No-Go Analysis
Concern about depreciation recapture
Hold-Sell Tax Impact Model
Possible missed historical depreciation
Depreciation Leakage Review
Property-tax, CAM, or utility leakage
Property Expense Leakage Scan
Weak insurance or asset documentation
Property Asset Intelligence Review
CPA or investor uncertainty
CRE Tax Opportunity Second Opinion
Ranking competing opportunities
Most properties produce more possible projects than an owner can execute at once. Five factors decide the order. A simple priority score helps, but it does not replace judgment — and tax or legal conclusions must not be accelerated merely because the owner wants an immediate answer.
Economic impact
Annual cash flow, one-time recovery, value effect, or risk avoided.
Speed
A billing correction hits the next invoice. A refinance takes months.
Confidence
A signed lease clause outranks an untested market-rent opinion. A preliminary estimate is not a completed study.
Cost and disruption
Some items need only better controls. Others need construction, legal work, lender approval, or a paid study.
Dependency
A refinance may wait on stabilized occupancy. A tax review may wait on locating invoices.
Part Five turns the scan into a report architecture and an annual plan.
Part three · fifty strategies
Fifty ways to improve cash flow and value, each in the same five-part format.
Purpose and measures affected. Application. Economic test. Decision control. Verification. Every strategy states which measures it moves — and which it does not.
Increase property income
Strategies 1–10- ›Rent and loss-to-lease audit
- ›Market-rent and renewal discipline
- ›Ancillary income review
- ›Parking and storage monetization
- ›Billing and collection controls
- ›Lead-response standard
- ›Make-ready cycle reduction
- ›Renewal and retention program
- ›Space or unit mix optimization
- ›Tenant experience and service recovery
Reduce expense leakage
Strategies 11–20- ›Utility benchmarking
- ›Vendor contract rebid
- ›Preventive maintenance
- ›Staffing and scheduling review
- ›Insurance risk-data improvement
- ›CAM reconciliation
- ›Lease expense-recovery audit
- ›Property-tax review and appeal analysis
- ›Utility submetering or allocation
- ›Delinquency and bad-debt controls
Make capital improvements pay
Strategies 21–30- ›CapEx priority scoring
- ›Yield-on-cost hurdle
- ›Renovation sequencing
- ›Tenant-improvement economics
- ›Energy and building-system upgrades
- ›Cost segregation feasibility review
- ›Lookback depreciation review
- ›Partial asset disposition review
- ›Repairs-versus-capitalization review
- ›Bonus depreciation and QIP review
Strengthen financing, risk, and exit readiness
Strategies 31–50- ›Refinance-readiness plan and loan-term comparison
- ›Debt-service and maturity ladder
- ›Reserve adequacy and capital-stack review
- ›Lease escalation design
- ›Effective-rent analysis
- ›Free-rent and concession control
- ›Tenant-credit and guarantee review
- ›Rollover concentration management
- ›Monthly KPI dashboard and variance process
- ›Hold-sell-refinance model and recapture-aware exit
Rent, renewal, and lease pricing discipline
The highest quoted rent may not produce the strongest effective economics.
Six of the fifty strategies govern how rent is set, raised, conceded, and renewed. The standard throughout is effective rent, not face rent — and a projected rent increase is never treated as created value until executed leases, collections, and market evidence support it.
Rent and loss-to-lease audit
Build a space-by-space schedule of market rent, contract rent, concessions, billed rent, and collected rent, then investigate every material variance. Loss to lease is not automatically recoverable — it tells you where pricing and contractual income differ. Run it by suite, never only in total.
Verification · Executed leases, billing records, deposits, aging, trailing operating statement.
Market-rent and renewal discipline
Maintain dated comparables and a renewal calendar. Begin renewal decisions early enough to compare retention against downtime, improvement allowances, commissions, and achievable rent. Record the reason for every pricing decision so it can be reviewed later. The highest quoted rent may not produce the strongest effective economics.
Verification · Dated comparable set, renewal calendar, written pricing rationale per suite.
Effective-rent analysis
Convert all rent, concessions, tenant improvements, commissions, downtime, and recoveries into one lease-term cash-flow comparison. Compare proposals on effective rent and expected NOI rather than face rent, and show the remaining exposure if the tenant defaults before you recover your investment.
Verification · Executed lease, delivery obligations, tenant costs, commencement, billing, recoveries.
Free-rent and concession control
Require every concession to show its economic cost, the lease term, tenant credit, market evidence, the approval, and the effect on effective rent. A concession granted without that file is a permanent discount nobody re-examines.
Verification · Concession approval record and its measured effect on effective rent.
Lease escalation design
Model fixed increases, indexed increases, expense recoveries, market resets, caps, floors, and tenant affordability across the whole term. An escalation negotiated once pays every year without another conversation.
Verification · Executed lease terms, billing setup, recovery calculations.
Rollover concentration management
Plot lease expirations by month, year, area, revenue, tenant credit, and renewal probability. Address concentrations before your lender and your buyer do.
Verification · Rollover and exposure report, updated at each executed lease.
All fifty strategies carry the same economic test and verification standard.
Worked calculations from the book
Five decisions, each carried all the way to the number.
Quantifying the opportunity — Capital Recovery Scan, Step 4
Four candidate items surfaced on the anchor property. Each is stated with dollars, timing, cost, and confidence — and none is added to another until it is classified.
| Lease audit — missed annual billings | $18,000 |
| Vendor rebid — high-confidence annual saving | $9,000 |
| Refinance — annual debt service reduction | $15,000 |
| Refinance — closing cost required | −$80,000 |
A recurring saving, a one-time recovery, financing proceeds, and a tax timing effect are four different results. Label each one. A sustained NOI increase may support a value increase, but you cannot count the annual income and the full value estimate as two independent piles of cash.
Durable NOI improvement translated into value — Measure 12
A $25,000 NOI increase, tested for durability and capitalized at a market-supported 8 percent.
| Durable NOI increase | $25,000 |
| Market capitalization rate | 8.00% |
| Indicated value effect | $312,500 |
| Status | Indication, not appraisal |
Only durable NOI changes support value, and the cap rate is an assumption you have to defend. Document the change, its durability, and the rate used. An owner cannot simply select a lower cap rate.
Why timing has a price — the present value illustration
$600,000 of deductions at an illustrative 32 percent tax-effect rate. Alternative A delivers the full effect now. Alternative B delivers $60,000 of deductions at each year-end for ten years.
| Alternative A — effect now | $192,000 |
| Alternative B — $19,200 per year for 10 years | $192,000 |
| Present value of B at an 8% discount rate | ≈$128,800 |
| Indicated timing advantage of A | ≈$63,200 |
Before study cost, tax-preparation cost, state treatment, limitations, and disposition consequences. This is a finance illustration, not a MACRS schedule. A real analysis uses the actual depreciation schedules and tax assumptions.
The full-hold comparison — why recapture does not automatically erase timing value
Action case against no-action case, same sale date, same assumptions, differences discounted to the decision date.
| Earlier after-tax liquidity from the action case | $160,000 |
| Future value at an illustrative 6% over five years | ≈$214,100 |
| Additional tax at sale versus no action | −$145,000 |
| Simple difference at year five | ≈$69,100 |
Before study cost and before tax on reinvestment returns. Future recapture does not automatically erase timing value — and a short hold narrows the margin fast. A proper analysis discounts every difference to the decision date.
The anchor exit schedule — transaction cash is not taxable gain
Assume a sale after five years at $3,800,000 with 6 percent selling costs and a scheduled loan balance of approximately $1,910,000.
| Sale price | $3,800,000 |
| Selling costs at 6% | −$228,000 |
| Net proceeds before debt and tax | $3,572,000 |
| Cash before income tax, after loan payoff | ≈$1,662,000 |
Those figures describe transaction cash. The tax schedule is separate: with an illustrative $2,170,000 adjusted basis, preliminary aggregate gain before class-by-class character analysis would be $1,402,000, which the CPA then allocates across Section 1245 recapture, Section 1250 treatment, unrecaptured Section 1250 gain, and state effects.
Four false positives
The language of hidden money can encourage bad decisions.
What it looks like
What it actually is
Gross value presented as available cash
Equity is reduced by debt, transaction costs, taxes, lender constraints, and your own willingness to sell or borrow.
A deduction presented as permanent savings
Depreciation timing, usability, limitations, and future disposition can all change the economic result.
Deferred maintenance presented as an expense saving
An unpaid obligation is not recovered capital. It is a bill with a later date on it.
A projected rent increase presented as created value
Not until it is supported by executed leases, actual collections, and market evidence.
The scan earns trust by removing weak opportunities as well as identifying strong ones. Recovered capital and created value are also different things: a sustained NOI increase may support an indicated value increase, but you cannot count the annual income and the full value estimate as two independent piles of cash.
Part four · cost segregation
A credible analysis can say no.
Cost segregation can change the timing and classification of depreciation deductions. It does not by itself increase NOI, solve weak operations, change a loan contract, guarantee usable losses, or eliminate sale and recapture consequences. Five gates decide whether it fits.
Property eligibility
Business or income-producing use, ownership, depreciable basis, property type, placed-in-service facts. Identify prior studies, personal use, related-party issues, and assets already separately stated.
Allocation potential
A reasonable range of basis that may fall into shorter-life classes, from property characteristics and available records — not a guaranteed percentage. Show a low, expected, and high case when uncertainty is material.
Tax capacity
How much of the incremental deduction is expected to be usable, and when. The property owner, the entity, and the ultimate taxpayer may not share the same limitations. This is CPA input, not an assumption.
Economics
Present value of incremental tax effects against study cost, CPA implementation cost, internal time, and future compliance — measured incrementally over the baseline schedule.
The full holding period
Expected sale date, adjusted basis, allocation of proceeds, depreciation-related gain, suspended losses, and alternatives. A near-term sale is not an automatic no, but it raises the level of proof required.
The anchor property allocation
An illustrative preliminary allocation of the $2,400,000 depreciable basis, with the $600,000 land allocation kept separate.
| 5-year property | $330,000 |
| 7-year property | $30,000 |
| 15-year property | $240,000 |
| 39-year nonresidential real property | $1,800,000 |
| Short-life total | $600,000 |
The allocation alone does not tell you the current-year tax result. The study answers the asset question. The tax model answers the taxpayer question.
The anchor property result
| Depreciable basis | $2,400,000 |
| Possible shorter-life property | $600,000 |
| Incremental deduction usable this year | $350,000 |
| Tax effect at an illustrative 32% | $112,000 |
| Study and implementation cost | −$12,000 |
| Expected hold | 7+ years |
On those facts the preliminary result is yes, subject to normal verification. Change two facts — a sale expected in twelve months and no current ability to use the loss — and the same property becomes conditional or no. The decision should not rely on a deduction that stays suspended until disposition.
Four misconceptions
“My CPA already did this — the property is on a depreciation schedule”
A normal schedule may show building, land, equipment, and known improvements without the component analysis that identifies additional shorter-life property. The question is whether a prior engineering or detailed asset-classification study was performed, not whether depreciation exists.
“Every building produces a predictable allocation”
Low basis, simple construction, weak records, a prior study, personal use, ownership structure, or an approaching sale may all reduce the value. A feasibility review should precede a full study when the economics are uncertain.
“Accelerated depreciation equals immediate cash”
A deduction affects cash only through a return and only when the taxpayer can use it. Basis, at-risk, passive-activity, excess-business-loss, entity, and state rules may limit or defer the effect. A credible analysis shows deduction generated and deduction usable as separate amounts.
“A study guarantees audit protection”
No report prevents examination or guarantees an outcome. A well-supported study improves the documentation available to the taxpayer and the preparer. The proper promise is a documented process, not immunity from review.
Appendix D, free, with the 30-measure quick reference.
[Author photo placeholder]
[Years in commercial property and finance — to be supplied]
[Professional credentials — to be supplied]
[Properties or engagements analysed — to be supplied]
The author note, in his own words
What is really happening underneath the numbers?
I have spent much of my career looking at complicated financial and business problems and asking a practical question: what is really happening underneath the numbers? Commercial real estate rewards that habit. A property can look successful while cash, value, time, or tax efficiency is being lost inside the operation.
This book grew from that question. It is not an argument that every property needs every strategy, and it is not a promise that cost segregation solves every problem. It is a system for seeing the property clearly, measuring the opportunity, and knowing when the facts support action.
I want you to use the equations, worksheets, and examples, but I also want you to challenge them. Replace the assumptions with your facts. Ask what changes if rent growth slows, a loan reprices, a tenant leaves, a project runs over budget, or a deduction cannot be used immediately.
The objective is not to make the property look better on paper. The objective is to make a better decision.
— Geoff Thompson
On owning versus controlling: title gives you legal and economic rights, but operational control comes from timely information and enforceable procedures. An owner who cannot obtain a current rent roll, explain a large variance, locate the loan maturity, or reconcile the fixed-asset schedule is depending on others without a way to verify their work. The answer is not micromanagement. It is a reporting standard.
Inside the book
Five parts, in the order an owner should investigate a property.
Part One
The capital inside the property
The four economic engines, the six places capital becomes trapped, the Capital Recovery Scan, and the controlled property record.
Chapters 1–3
Part Two
The 30 measures that explain the property
Income, value, debt, investor returns, and tax — each measure with definition, equation, anchor figure, decision use, and owner action.
Chapters 4–8
Part Three
Fifty ways to improve cash flow and value
Each strategy with purpose, application, economic test, decision control, and verification. Income, expenses, capital, then financing and exit.
Chapters 9–12
Part Four
Cost segregation, tax timing, and full-hold economics
What a study actually does, bonus depreciation and the time value of deductions, the five-gate go or no-go, lookback studies, and disposition.
Chapters 13–17
Part Five
From study to property optimization
The engineering study and professional team, the Capital Recovery Analysis report architecture, and the annual optimization plan.
Chapters 18–20
Appendices
Quick reference, checklists, worksheets, glossary
30-measure quick reference, 50-strategy annual checklist, document checklist, go or no-go worksheet, capital recovery worksheet, glossary, review controls, disclaimer.
A–H
The eight appendices
- Appendix AThe 30 Measure Quick Reference
- Appendix BThe 50 Strategy Annual Checklist
- Appendix CCost Segregation Document Checklist
- Appendix DCost Segregation Go or No Go Worksheet
- Appendix ECommercial Property Capital Recovery Worksheet
- Appendix FGlossary
- Appendix GAssumptions, Sources, and Review Controls
- Appendix HProfessional Disclaimer
Records to gather before you start
- ›Current rent roll and all active leases
- ›Trailing twelve-month income and expense statement
- ›Current-year budget and acquisition pro forma
- ›Loan agreement, amortization schedule, and maturity date
- ›Closing statement and purchase-price allocation support
- ›Fixed-asset and depreciation schedules
- ›Improvement, tenant-buildout, and major repair invoices
- ›Recent value evidence, insurance schedule, and property tax records
Early readers
Endorsements will appear here.
These are placeholders. Nothing below is a real endorsement, and nothing will appear here until the words are genuinely someone else's.
[Reader endorsement to be added]
[Reader endorsement to be added]
[Reader endorsement to be added]
Free download
The Capital Recovery Toolkit.
Five working references pulled straight from the appendices, so you can run the first pass on your own property before you read a page.
- ›Appendix A — the 30 Measure Quick Reference
- ›Appendix D — the Cost Segregation Go or No-Go Worksheet
- ›The Capital Recovery Scan seven-step sheet
- ›The records-to-gather checklist for a full property review
- ›The five-factor opportunity ranking sheet
Questions
Before you buy it.
No. Cost segregation occupies one part of five. The book does not begin with “do you need a study?” It begins with “what is happening inside the property?” A study is evaluated only after the operating and financial baseline exists — and the framework has to be able to say no.
Separate the forces. Measure them correctly. Decide what deserves action.
Thirty measures, fifty strategies, five decision gates, eight appendices, and one property carried from the first page to the last.